A clear look at Gatepass versus traditional mortgages in Kenya and how flexible land-first ownership is changing how Kenyans buy property.

Why This Comparison Matters
Look, buying property in Kenya can feel heavy. You talk to a bank. You hear about interest rates, long forms, payslips, guarantors, insurance, valuation fees. Then someone else tells you about flexible ownership models that sound simpler but raise questions.
So this article breaks things down. Slowly. Clearly.
Gatepass on one side. Traditional mortgages on the other.
No fear tactics ➝ Only how each path works and who tends to benefit.
If you’ve ever wondered whether a mortgage is the only serious way to own property, keep reading.
How Traditional Mortgages Work In Kenya
A mortgage in Kenya usually starts with a bank or SACCO. The process follows a familiar route.
You identify a property.
The lender evaluates the value.
You provide proof of income.
A deposit is required, often 10–20 percent.
Interest is applied over 15 to 25 years in most cases.
Monthly repayments are fixed or variable depending on the lender and economic conditions.
Mortgages work best for people with:
Stable, documented income
Strong credit history
Ability to commit long-term
Banks play an important role in the housing market. Many homeowners rely on mortgages and succeed with them. Still, the process asks for patience, paperwork, and financial predictability.
Where Mortgages Tend To Feel Heavy
People often pause when:
Approval takes longer than expected
Income verification becomes complicated
Interest rates change mid-loan
Monthly payments stretch household budgets
Kenya’s mortgage penetration remains low compared to population size. Central Bank of Kenya data shows uptake has grown slowly over the years.
Mortgage uptake in Kenya remains relatively low compared to population size, according to data from the Central Bank of Kenya and Kenya Mortgage Refinance Company (KMRC).
These realities push many buyers to explore other ownership paths.
What Gatepass Does Differently
Gatepass approaches ownership from the ground up. Literally.
Instead of starting with a completed house and a bank loan, Gatepass begins with verified land. Clean documentation. Clear boundaries. A payment plan that fits real monthly income patterns.
You choose a plot.
You agree on a payment plan.
You start paying immediately.
Ownership progresses step by step.
There’s no credit scoring. No bank interviews. No guarantors.
This model works especially well for people who want control over pace and planning.
Gatepass follows a clear, step-by-step ownership process that starts with verified land and flexible payment plans.
Learn More Here ➝ How Gatepass Works
Payment Structure: A Practical Difference
With traditional mortgages:
Deposits are upfront
Interest compounds over long periods
Monthly payments may change with market rates
With Gatepass:
Payments are structured and transparent
Timelines are shorter
Costs are known from the start
Someone paying KES 23,000 per month or less can realistically plan around school fees, rent, and transport. That predictability matters.
Ownership Timeline & Flexibility
Mortgages often span decades.
Gatepass plans usually range from months to a few years.
Shorter timelines mean:
Faster equity
Earlier control
Freedom to build when ready
Land-first ownership gives space to plan construction separately, on your own terms.
One example is Stonecrest Gardens Gate A in Lukenya, a residential project offering 50×100 plots with individual freehold titles and structured payment options.
Documentation & Trust
Trust sits at the center of property decisions.
Gatepass focuses on:
Verified freehold title deeds
Transparent allocation
Open site visits
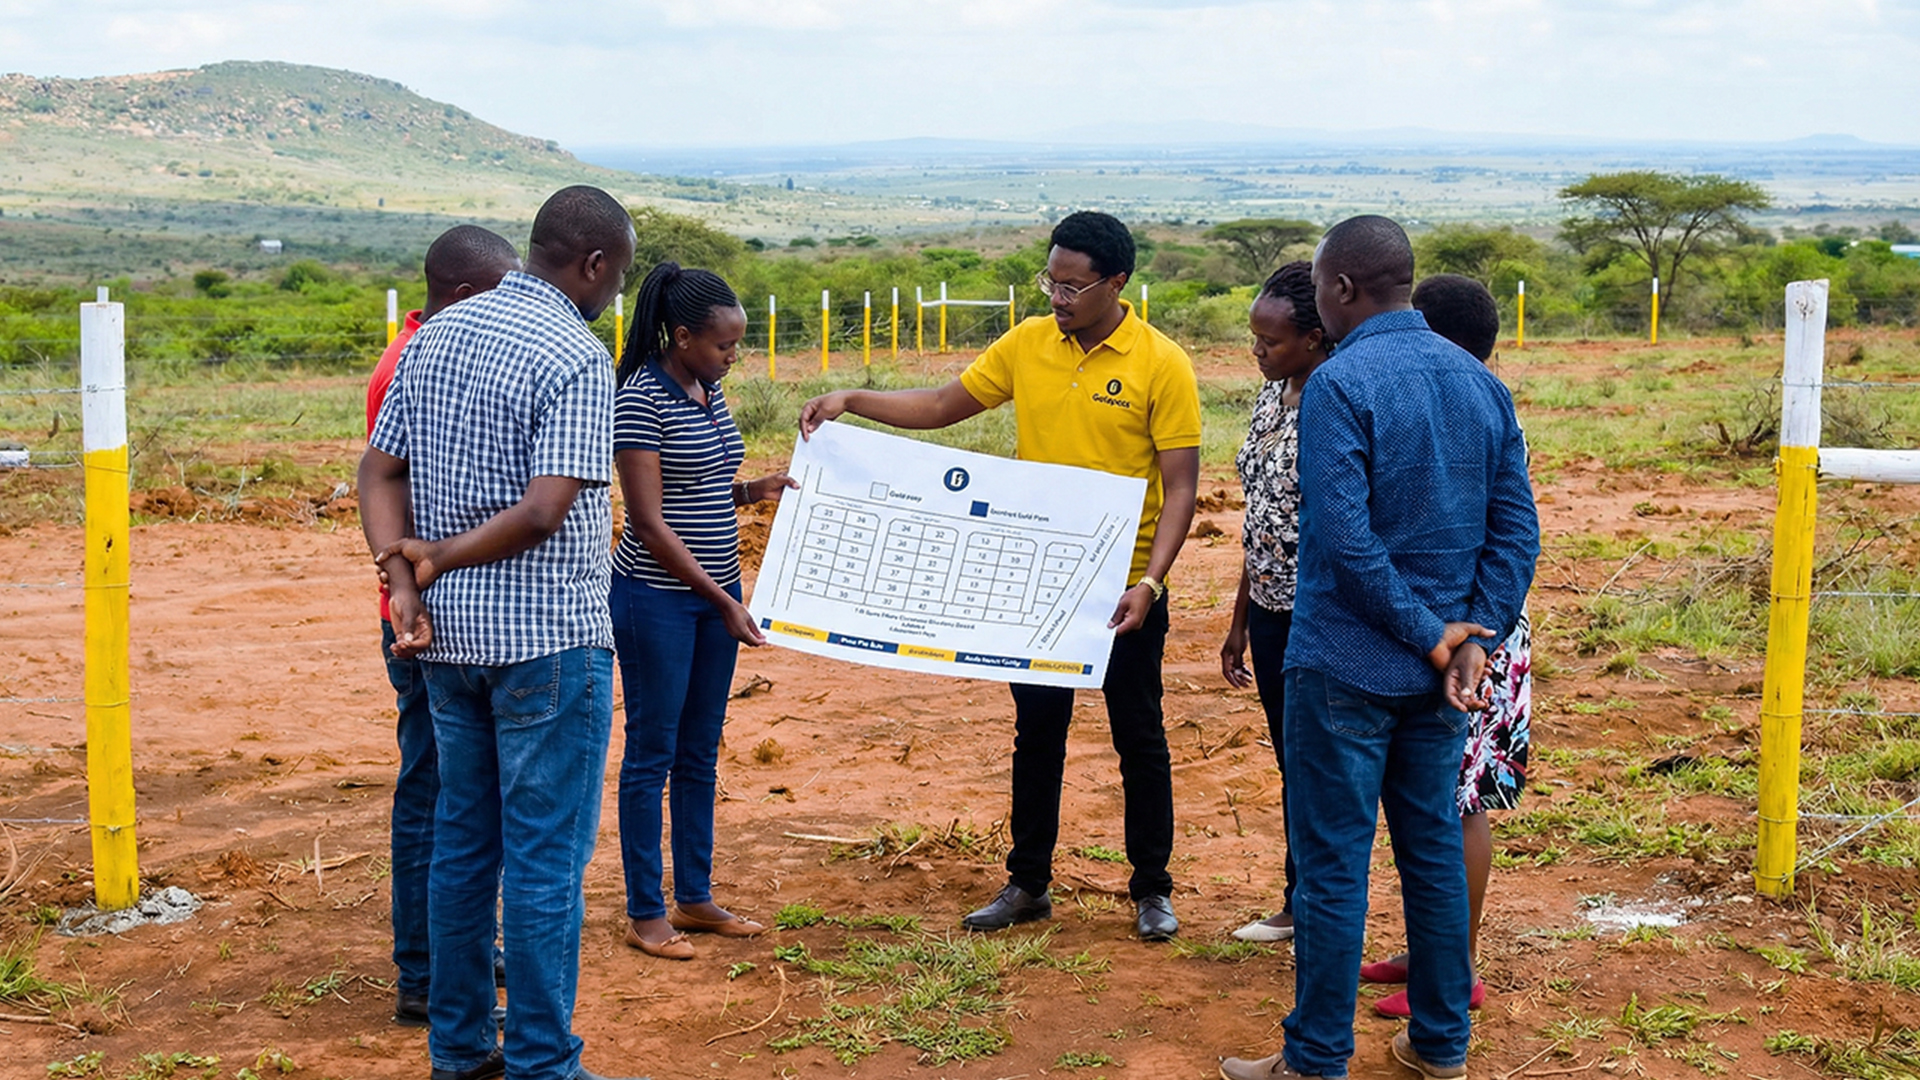
Clear subdivision maps
This helps buyers see exactly what they’re paying for. Many clients visit the land before committing.
Mortgages also involve strong legal frameworks, but the paperwork can feel distant for first-time buyers.
Who Gatepass Works Best For
Gatepass tends to suit:
Young professionals
Diaspora Kenyans
Self-employed individuals
First-time land buyers
Families planning gradually
People who value clarity and pace often lean this way.
Who Traditional Mortgages Still Serve Well
Mortgages still make sense for:
Buyers seeking completed homes immediately
People with long-term salaried income
Those comfortable with long repayment horizons
Each path has a place in Kenya’s housing ecosystem.